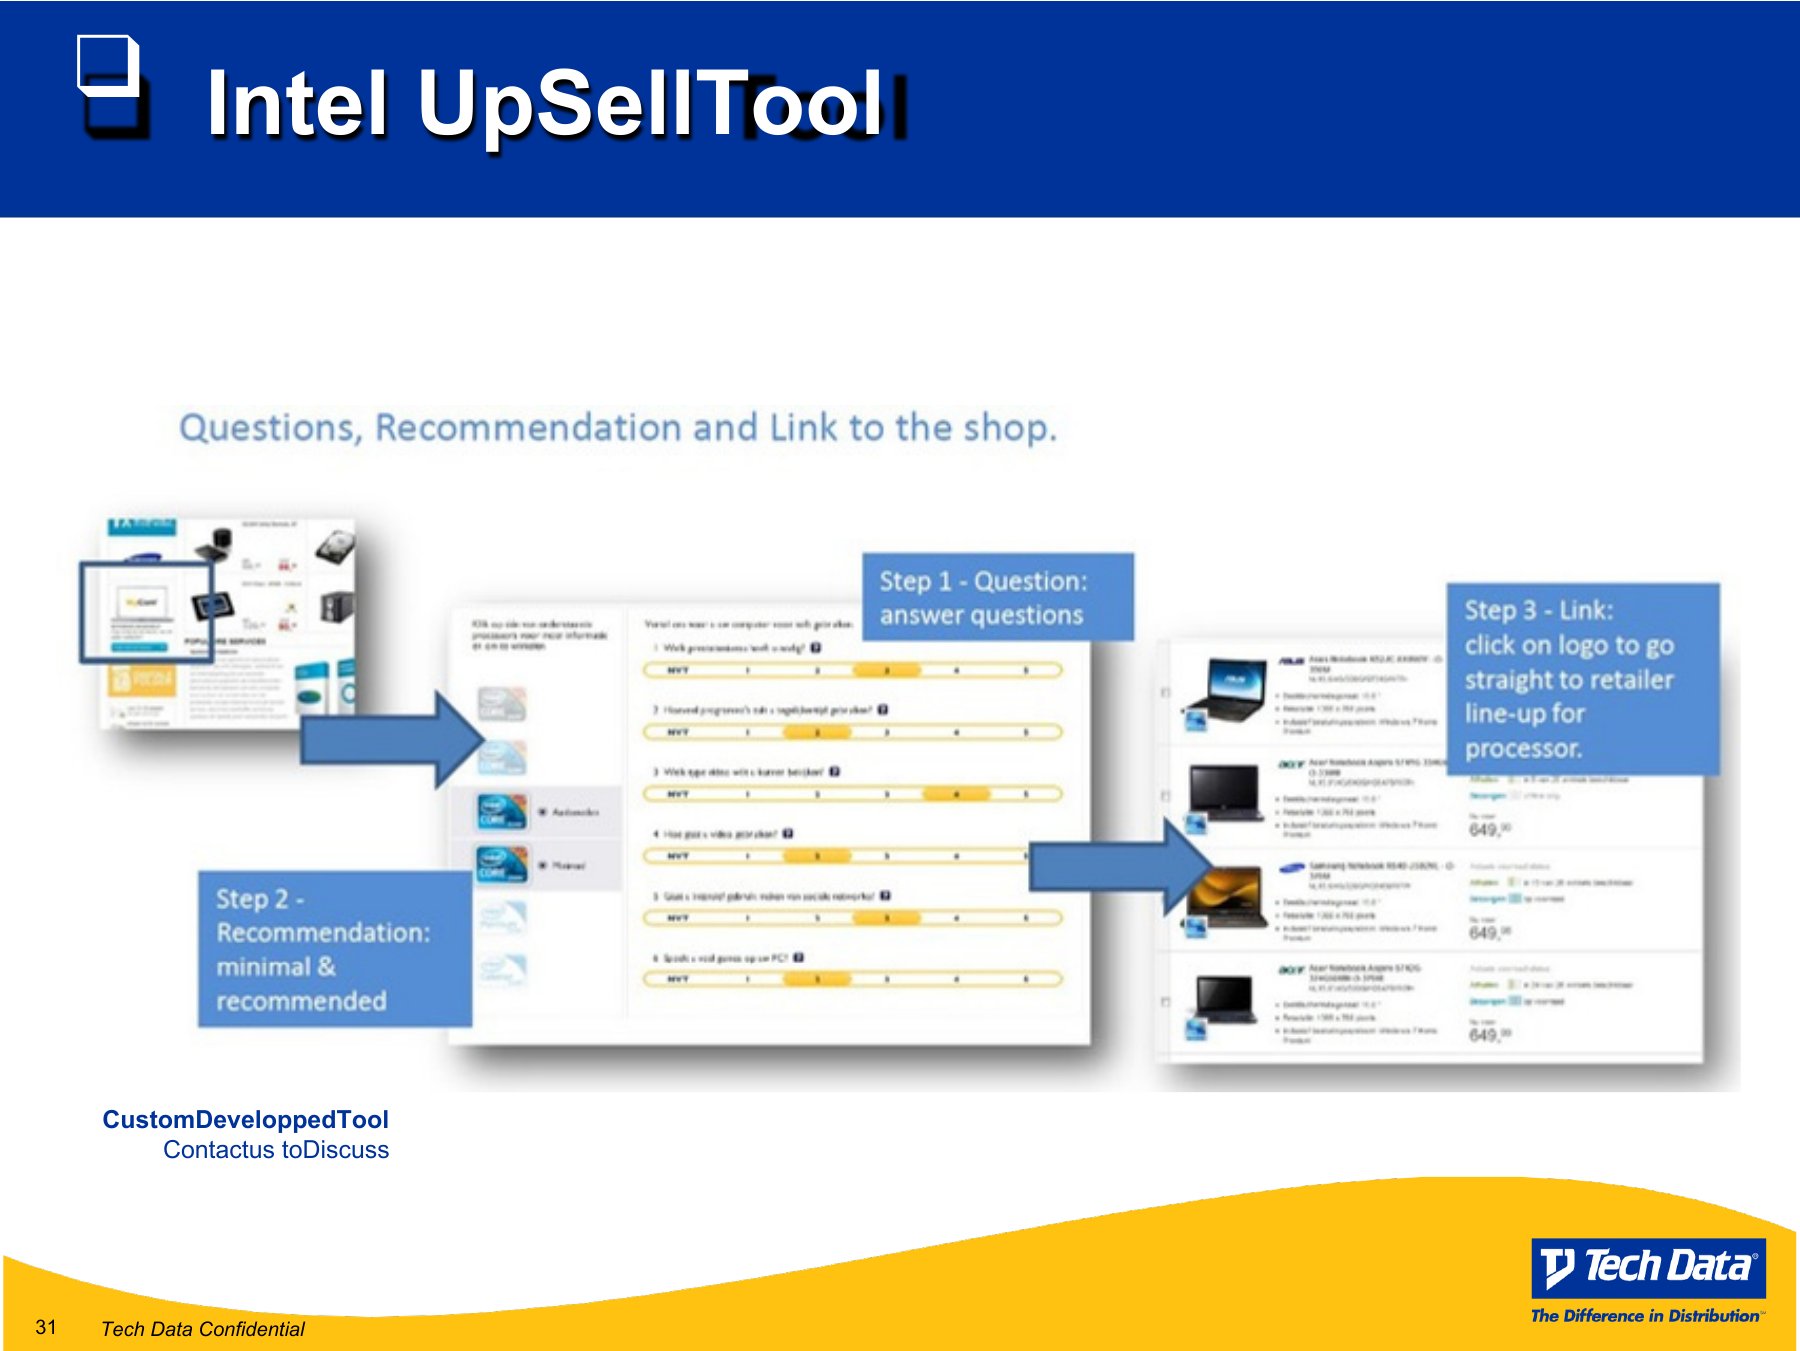
Intel (via TD Synnex)
We kept cutting the price. Customers still wouldn’t buy.
About
Intel (via TD Synnex)
Execution
Positioning
Product Marketing Manager
50% market share across components and 50–60% Intel share by rebuilding the commercial system.
Situation
A weak market position with an apparently simple explanation
When I joined Tech Data, Intel represented a surprisingly small part of the business. For a brand with such a dominant position in the PC market, our share as a distributor was weak at roughly 17 percent. The initial explanation inside the business was straightforward: we were not competitive enough on price, so stronger commercial conditions should help recover volume.
That assumption drove the first response. Pricing was sharpened, exceptions were made, and customer conditions were improved wherever possible. The difficulty was that many of the expected orders still did not materialise, which suggested that the problem was not being fully understood.
Looking beyond the internal diagnosis
Rather than continuing to adjust pricing, I began speaking directly with some of our largest customers to understand why they were still placing business elsewhere. The purpose of those conversations was not to persuade them to buy from us, but to understand the practical reasons behind their purchasing decisions.
A consistent pattern emerged. Customers were not buying processors as standalone products because they were assembling complete PCs and needed motherboards, memory, chassis, graphics cards and other components around the CPU. If they bought Intel from Tech Data but sourced the rest of the system from another distributor, they created additional purchase orders, deliveries, administrative work and shipping costs.
The issue was therefore broader than processor pricing. We were trying to optimise one element of the transaction, while customers were evaluating the cost and convenience of the entire purchasing process.
Reframing the source of growth
Once that became clear, further price reductions made much less sense. The commercial constraint was not located within the Intel offer itself, but in the surrounding system of products and services available to the customer.
The implication was that category growth would depend on making Tech Data a more complete purchasing partner. That required broadening the components portfolio so customers could source more of the system from one place, rather than splitting orders across several distributors.
This was not simply an assortment exercise. Each additional category needed to remove a practical reason for customers to buy elsewhere and strengthen the overall value of purchasing through Tech Data.
Using customer demand to shape the portfolio
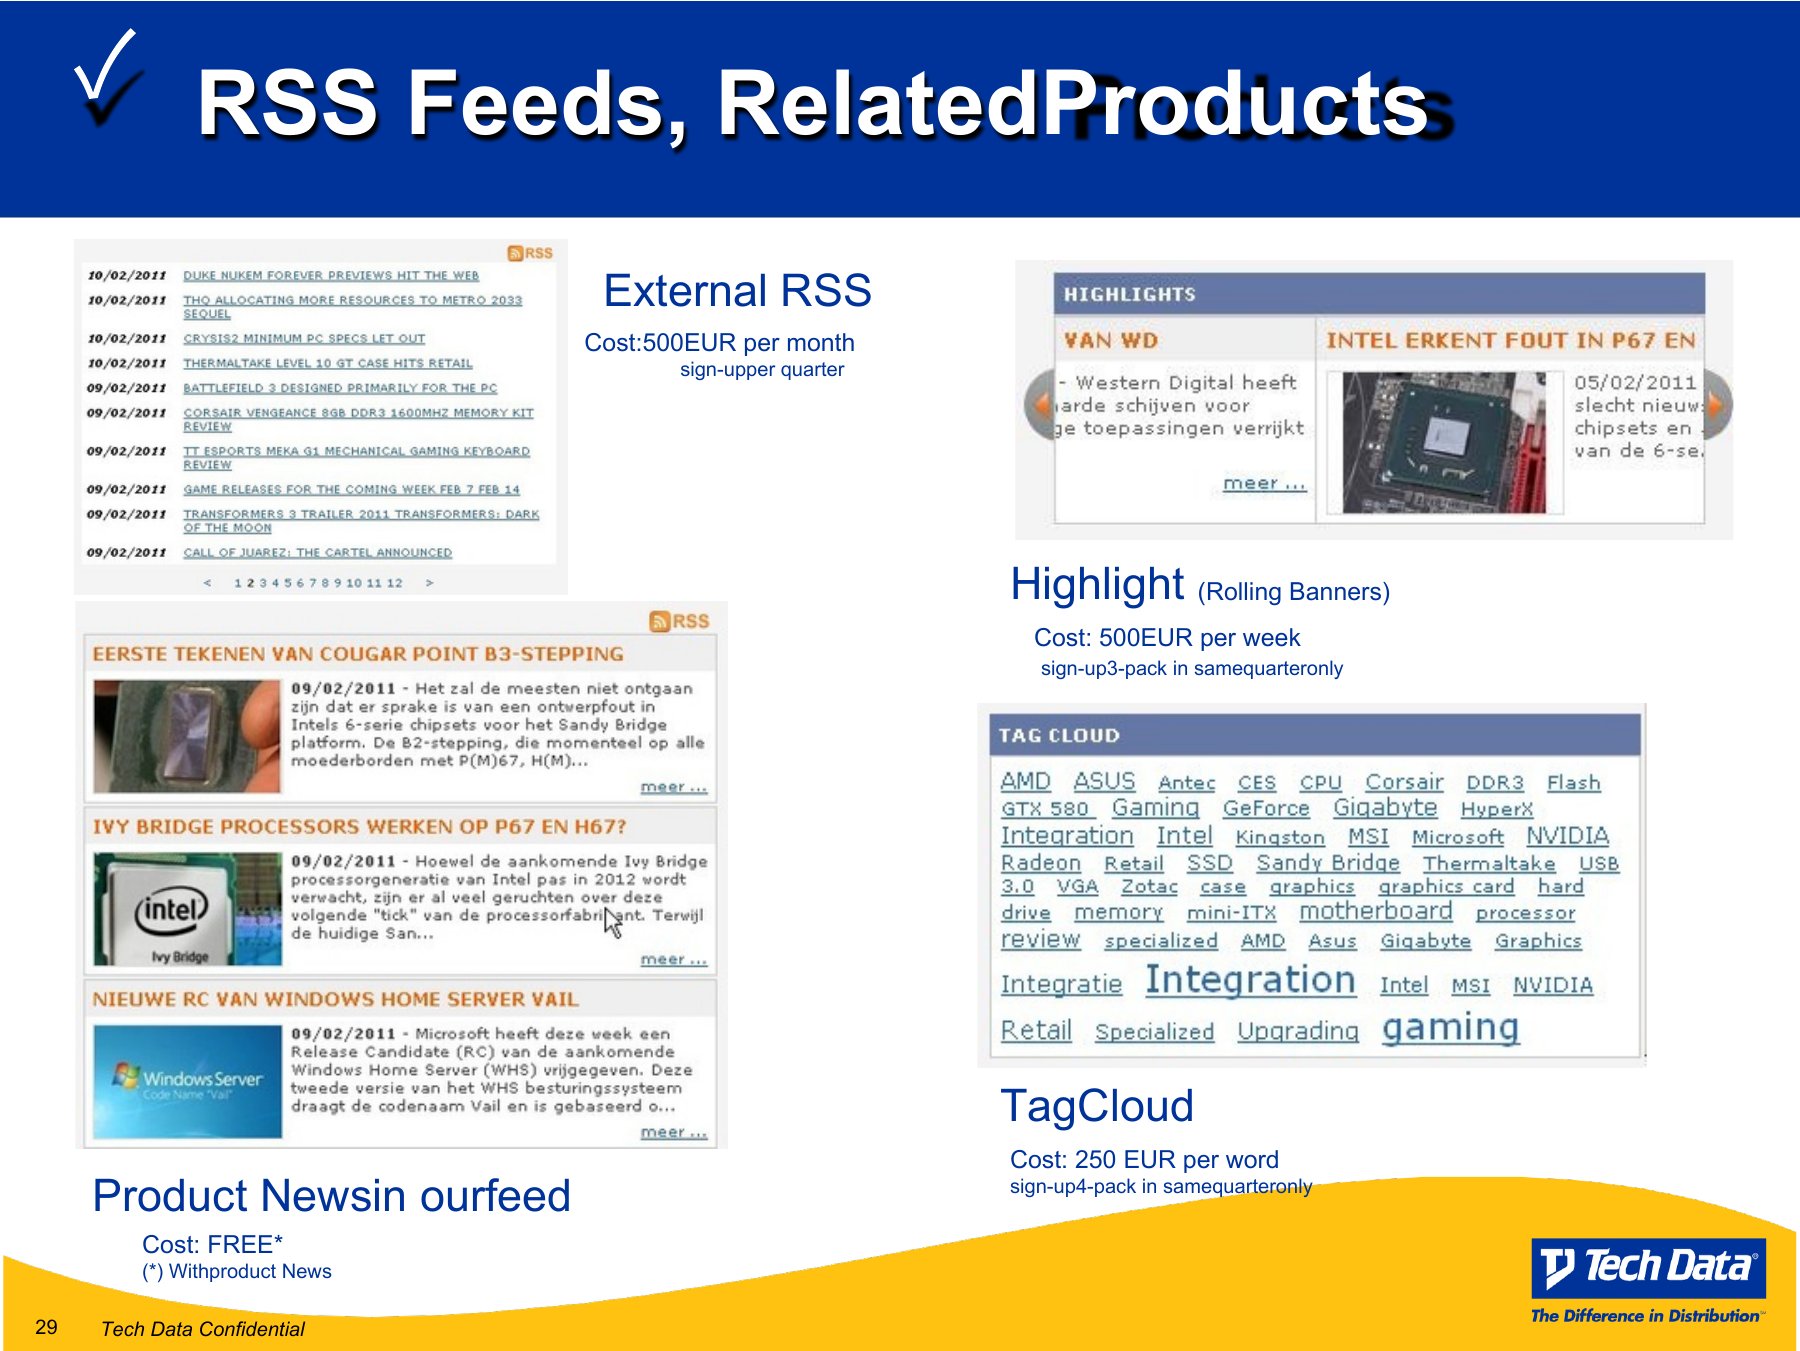
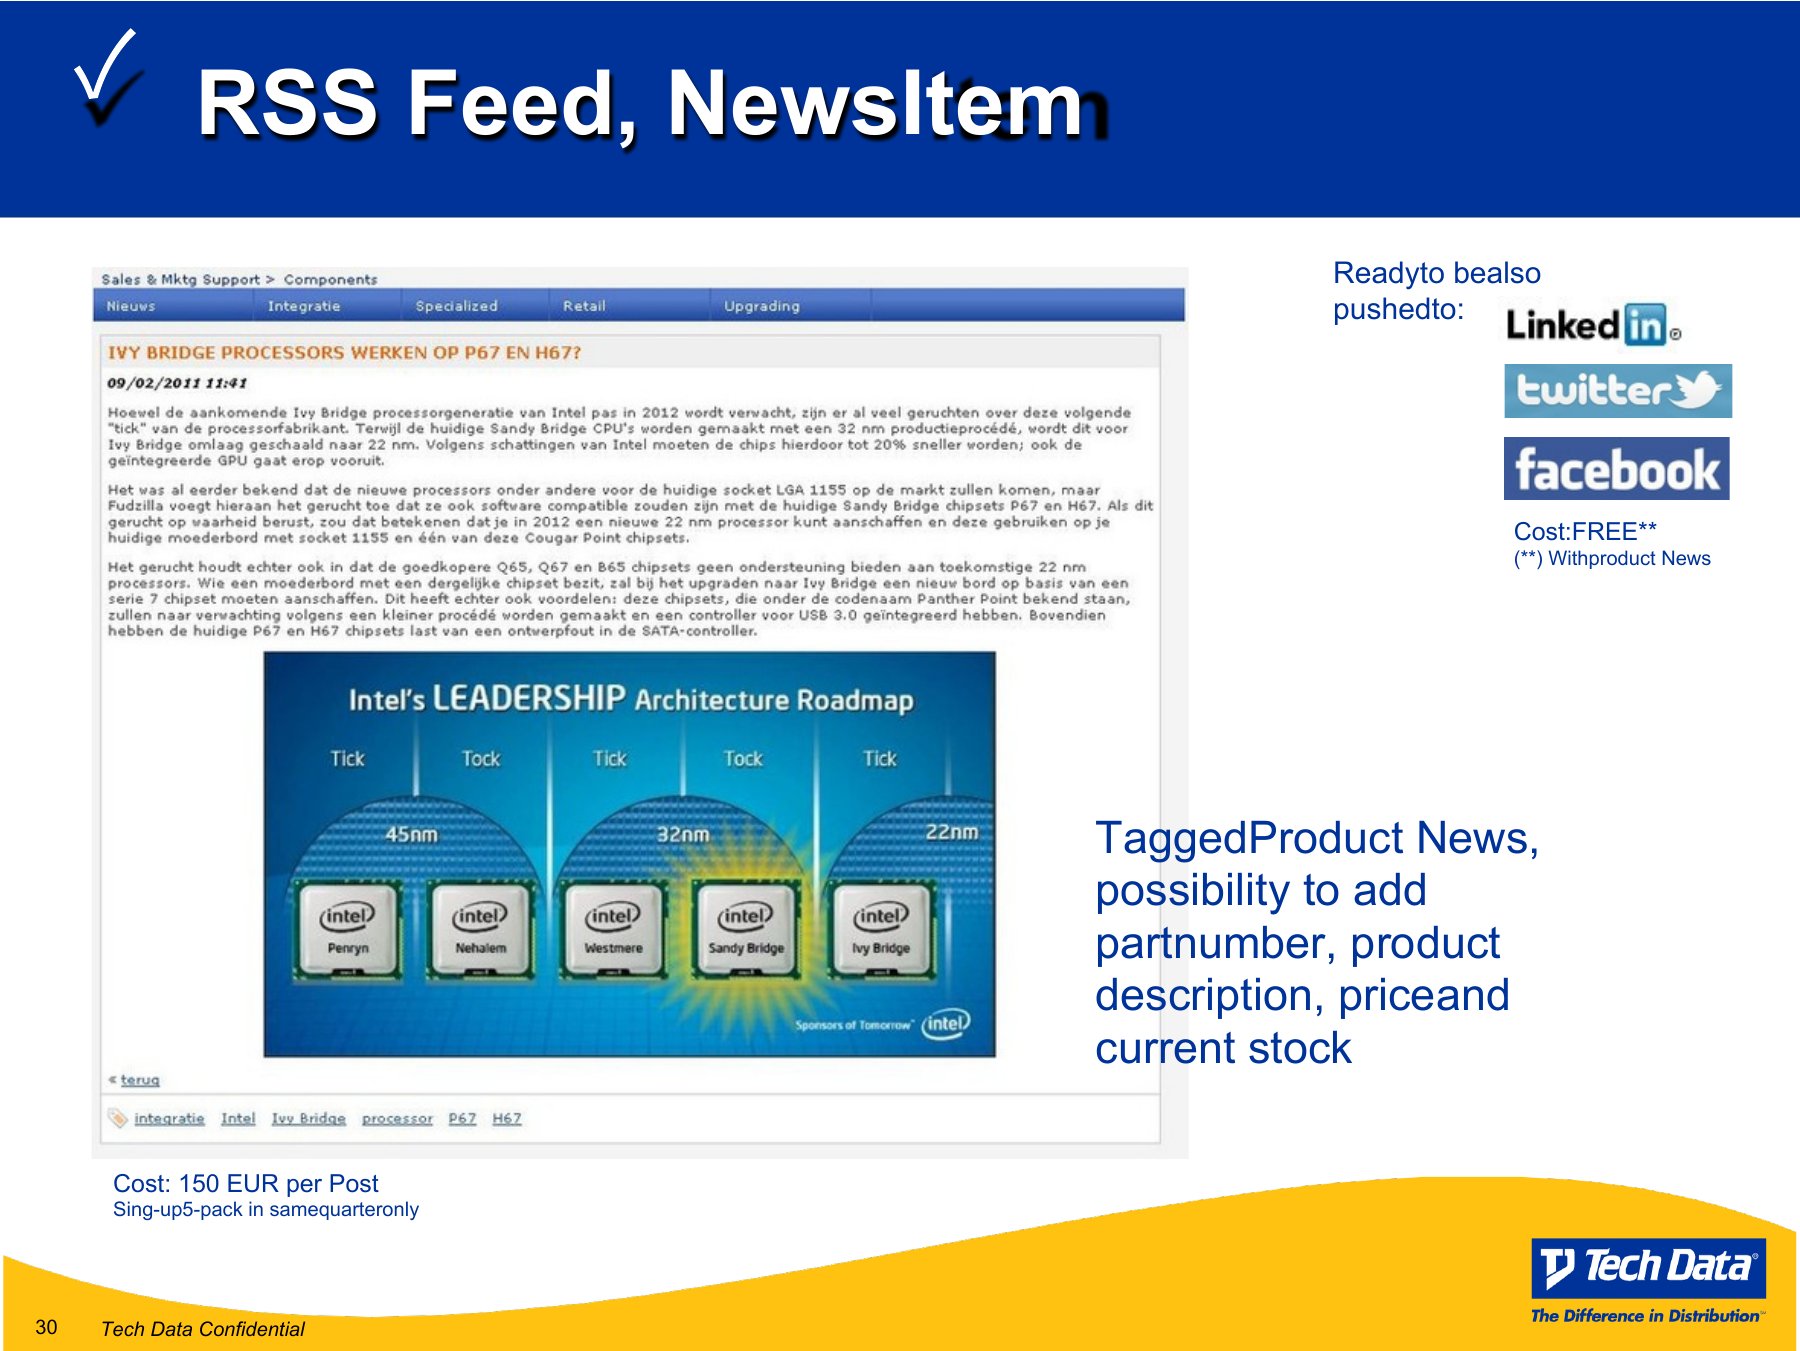
The new direction also changed the way Product Management worked with Sales. Rather than deciding centrally which products should be stocked and then asking Sales to move them, I increasingly used the sales team as a direct source of market intelligence.
The questions became more grounded in observable customer demand. We wanted to know which products customers were asking for, where gaps existed in the current portfolio, what pricing levels would make those products competitive, and how much volume the market could realistically absorb.
Peter Pieraert and the wider sales team became important contributors to those decisions because they had direct visibility into customer conversations. My role increasingly involved translating that demand into supply by identifying vendors, negotiating conditions, securing allocation, managing inventory and ensuring that the economics worked.
Building a more integrated category model
That created a different commercial model for the components business. Product Management became less about maintaining a line card and more about connecting demand, supply, pricing, availability and vendor relationships in a coordinated way.
The quality of decision-making improved because portfolio choices were increasingly based on what customers were already trying to buy. Sales provided the market signal, Product Management converted that signal into supply decisions, and the broader assortment made Tech Data more useful to customers.
As the portfolio expanded, those effects reinforced one another. Greater relevance created more customer conversations, those conversations produced better market information, and that information improved the next set of portfolio decisions.
Reducing the need to buy elsewhere
The commercial objective gradually shifted from increasing Intel sales in isolation to reducing the reasons customers still needed another distributor. Price remained important, but it became one factor within a broader proposition that also included assortment, availability, logistics and purchasing convenience.
This mattered because customers were not optimising individual SKUs independently. They were trying to simplify the overall process of building and supplying systems. The more completely Tech Data could support that process, the stronger the argument became for consolidating additional spend with us.
From 17 percent share to a leading category position
Over time, Tech Data moved from one of the smaller distributors in the category to roughly 50 percent market share across components, while Intel itself reached approximately 50 to 60 percent share.
The result reflected more than stronger vendor management or a larger product range. It came from changing the diagnosis of the problem and then restructuring the commercial offer around the way customers actually purchased.
The most important shift was therefore not from weak pricing to better pricing. It was from managing Intel as an isolated product line to managing the wider customer buying system around it.
Diagnosing the system before optimising the symptom
The experience became an important lesson in commercial problem solving. When repeated improvements to an obvious variable fail to change the outcome, the more useful response is often to revisit the original diagnosis rather than intensify the same intervention.
At Tech Data, pricing was visible, measurable and easy to adjust, which made it a natural place to focus attention. Customer conversations showed that the underlying constraint sat elsewhere.
Growth accelerated once we stopped trying to optimise a single product and started redesigning the surrounding system around the way customers actually bought.
Shift
- Refused to compete in overlapping categories to maintain trust
- Identified the real issue through direct customer conversations
- Rebuilt the offer around full component availability, not just CPUs
- Inverted the model: sales defined demand, marketing secured supply
- Built a joint decision model between sales and marketing on portfolio, pricing, and volume
Clarity Engine Alignment assessment
Results
- Grew from smallest to largest components distributor
- Achieved ~50% market share across components
- Increased Intel share to 50–60%
- Became the preferred one-stop-shop for system builders
- Created a scalable, repeatable distribution model
Defining moment
Direct customer conversations revealed the real issue: buying CPUs from Tech Data meant sourcing all other components elsewhere, increasing cost and complexity. That insight shifted the strategy from price competition to system completeness.
Client feedback
Testimonial
insights
Related
insights

Start with diagnose
Answer 6 questions. See where your commercial system is losing clarity.losing clarity.
A short diagnostic built on the Alignment Matrix. It points to where friction is most likely sitting — not a definitive answer.